Real Estate Bookkeeping
Real Estate Agent Bookkeeping: A Guide for 1099 Agents
Book each closing from the commission statement, tie out your 1099 and log 2026 miles at two IRS rates. Real estate agent bookkeeping, plus what it costs.
Certified Advanced QuickBooks Online ProAdvisor
Real estate agent bookkeeping comes down to three habits. Book every closing from your commission statement, not the bank deposit. Keep every business dollar in its own account. And reconcile every month, so your income ties to the 1099-NEC your brokerage sends and your CPA can set your estimated taxes from real numbers.
Skip them and January gets ugly. The brokerage took its cut before the money reached you. You paid for photos, signs and leads on whatever card was handy. Then the 1099 doesn't match your deposits, and your CPA wants a mileage log you never kept.
We checked every tax rule below against IRS and Pennsylvania sources on November 22, 2026.
Why real estate agent bookkeeping is different
Nobody withholds tax from your commissions. You owe income tax plus self-employment tax of 15.3% (12.4% for Social Security, 2.9% for Medicare), and you pay it yourself during the year.
That's because the IRS treats a licensed agent as self-employed for all federal tax purposes when substantially all of the pay comes from sales, not hours, and a written contract says the agent won't be treated as an employee. It's called the statutory nonemployee rule.
And the income is lumpy. Three closings in May, nothing in February. MLS dues and lead fees don't take February off.
Book every closing from the commission statement
If your brokerage pays you net, a transaction fee, a tech or E&O fee or a franchise fee can come out before the deposit lands. Book the deposit as income and those costs vanish.
Here's one closing. The statement shows your share as $9,000, minus a $450 transaction fee, and $8,550 hits your account. If your brokerage reports $9,000 on your 1099-NEC, the books need $9,000 of income and $450 of fees. Booked from the deposit they show $8,550. Five closings like that and your books are $2,250 short of the 1099, and nobody knows why.
The fix is boring. Enter every closing from the commission statement, line by line, and make sure the net equals the deposit. Ask your brokerage what its 1099 will include so your income line matches it.
Watch the calendar too. On the cash method, a commission check you receive December 30 is December income even if you deposit it January 4, because you can't hold a check to push income into next year. Book it on the date you received it.
Your brokerage's job is to send the 1099. Keeping your books isn't. And your CPA usually sees your numbers at tax time. So tying it all together every month falls to you, or to your bookkeeper.
What a real estate agent should track
Give each of these its own category in your books, with a receipt behind it. Your CPA decides how each one gets deducted.
- Brokerage costs: desk or cap fees, transaction fees, tech and franchise fees
- Dues and licensing: MLS, board and association dues, license renewal and continuing education. The IRS lists licenses and regulatory fees among expenses you may be able to deduct.
- Insurance: errors and omissions (E&O) coverage
- Marketing: listing photos, signs, ads, lead platforms, your website and CRM
- Phone and software, with any personal share split out
- Business parking and tolls, whichever method your CPA uses (they're deductible on top of the standard mileage rate, but parking at your regular workplace isn't)
- Car costs, if your CPA uses actual expenses: gas, oil, tires, repairs, insurance, registration and lease payments
- Home office: the office's square footage and your home's total square footage, plus rent or mortgage interest, real estate taxes, utilities, insurance and repairs, the numbers your CPA needs to figure a home office deduction
Client gifts: the $25 rule
Closing gifts have a hard limit. You can deduct no more than $25 a year for business gifts to each person. A $150 closing gift to one client still counts as $25. Wrapping and mailing don't count toward the limit. Items that cost $4 or less, carry your name and get handed out widely (pens, say) aren't counted as gifts at all.
Meals and entertainment
A client meal is generally 50% deductible if you're there and it isn't lavish. Taking a client to a game or concert is entertainment, and entertainment isn't deductible. Tickets you give a client when you don't go with them can count as a gift instead, so the $25 limit applies. Keep meals, entertainment and gifts in separate categories, with a note of who each gift went to.
Your car: 2026 has two mileage rates
The IRS changed the standard mileage rate halfway through 2026. Business driving from January 1 through June 30 uses 72.5 cents a mile. From July 1 on it's 76 cents, raised because fuel prices went up.
So the date on every trip matters. 5,000 business miles in each half of the year comes to $3,625 plus $3,800, or $7,425. A log with one total for the year can't be split that way. The IRS already wants the miles for each business use and your total miles for the year, so log the date, the miles, where you went and why.
A business bank account, and a separate one for taxes
Even the IRS says to keep a separate bank account for your business. Commissions go in, business costs come out, and paying yourself is a transfer instead of a mystery charge on the business card.
Then open a second account for taxes and move a share of each commission into it the day it lands. Your CPA should set that share. We don't calculate estimated taxes. Each quarter we send you and your CPA year-to-date numbers so the CPA can set the payment, and we record the payments in your books.
The fourth 2026 federal estimated payment is due January 15, 2027, unless you file your 2026 return by February 1, 2027 and pay the whole balance with it. Three months behind on your books? Then that payment is a guess.
Pennsylvania agents: state and local tax on commissions
Live in Pennsylvania and your net profit gets taxed by the state and locally too.
- State: Pennsylvania taxes net profits from a business or profession at 3.07%.
- State estimates: required once your Pennsylvania income not subject to withholding is expected to top $9,500 for the year ($292 in tax).
- Local: outside Philadelphia, your local earned income tax (municipality plus school district) covers net profits too. DCED's local tax lookup shows your rate and collector by address.
- Local estimates: under the Local Tax Enabling Act you declare estimated net profits, pay the tax in quarterly installments to your local tax officer, then file a final return.
- Philadelphia: residents pay the City's own Net Profits Tax instead, with its own return and estimated payments. Agents who live elsewhere but do business in Philadelphia owe it too, at the nonresident rate.
- Sales tax: none on your commissions. Real estate services aren't among the services Pennsylvania taxes.
Teams, S-Corps and a second company
Team leads who pay other agents
If you pay team agents yourself, you send their 1099s. For payments made in 2026, a Form 1099-NEC goes to each person you paid $2,000 or more, commissions included. Agents paid through their own corporation are generally an exception. The 2026 forms are due February 1, 2027, since January 31 falls on a Sunday. Get a W-9 before anyone's first payment. Our guide to the new $2,000 threshold has more.
An LLC alone doesn't change your taxes
You'll see it on agent forums: form an LLC and the self-employment tax goes away. It doesn't. A single-member LLC is ignored for federal income tax unless it elects otherwise, and the owner pays self-employment tax the same way a sole proprietor does.
S-Corp agents
Electing S-Corp status changes how you get paid, and it makes the books heavier. An S-Corp has to pay its shareholder-employees reasonable compensation before it makes non-wage distributions, so you're on payroll. The company files its own return, Form 1120-S. And the balance sheet has to be right, because payroll, distributions and shareholder loans all run through it.
Watch who gets paid, too. If the brokerage pays you personally but the S-Corp is supposed to earn the commission, the 1099 and the company's books won't match. Settle it with your brokerage and your CPA before the next closing.
We don't run payroll. Your payroll provider does, and we record and reconcile it. Whether the election makes sense for you is your CPA's call. Our S-Corp bookkeeping page covers what we handle.
Agents who buy rentals
A rental is a second set of books: income and expenses by property, plus a depreciation schedule. That's a different job from agent books, and our investor bookkeeping page covers it.
Does a real estate agent need a bookkeeper?
Honestly, not always. Close a handful of deals a year with one business account and one card, and QuickBooks or even a spreadsheet plus an hour a month can do the job.
Bring in help when:
- Your 1099 and your books don't match and you can't say why
- You pay agents on a team
- You've elected S-Corp status or own a second company
- You're months behind and an estimated payment is coming due
What it costs
Plans are flat monthly fees. A solo agent with one business and a handful of accounts would usually start on Essentials, from $399 a month (for businesses under about $500K in yearly revenue). An agent doing $500K to $1M a year, an S-Corp with payroll reports to record, or a team with more accounts may fit Growth, from $599. Scale starts at $1,199. We confirm your plan and exact price in writing after a look at your books, and the first month has a money-back guarantee. Details are on our pricing page.
Already behind? Catch-up bookkeeping starts at $399, quoted as one flat fee after a free look.
How we handle real estate agent bookkeeping
Our monthly bookkeeping for agents runs in QuickBooks Online:
- Every closing booked from the commission statement, with the net tied to the deposit
- Bank and card accounts reconciled every month
- Your profit and loss and balance sheet by the 15th
- Year-to-date numbers each quarter for you and your CPA, with estimated payments recorded
- 1099 tracking for agents you pay, and a year-end package for your CPA
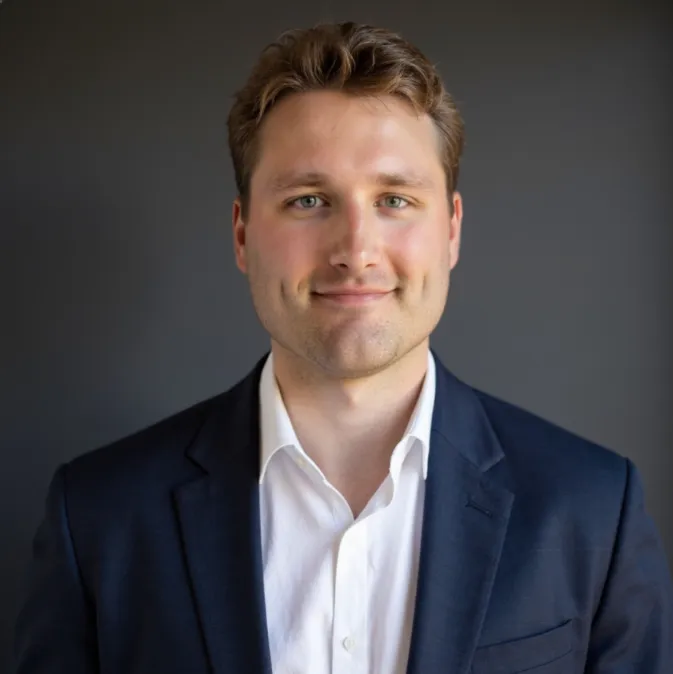
We don't prepare or file tax returns. Your CPA does, from clean books. You work directly with Jordan Peacock, Certified QuickBooks ProAdvisor. We're based in Cranberry Township, PA, north of Pittsburgh, and work with clients across the US, all online.
To start, call (412) 407-7420 or book a free intro call. We'll look at your books and put your plan and price in writing.
Written By
Ready to stop doing your own books?
No sales pitch. Just straight talk about your situation.
Related resources
Keep Reading
Related posts
7 min read
1099 Threshold 2026: The New $2,000 Rule and What to Do Now
For payments made in 2026, the Form 1099-NEC and 1099-MISC threshold is $2,000, up from $600. Here's which forms it covers, the real due date, who still doesn't get a form, what didn't change, where Pennsylvania stands, and what to do before December 31.
Jordan PeacockRead post9 min read
PA Estimated Tax Payments 2026: Next Deadline Is Jan 15, 2027
Most Pittsburgh-area business owners don't realize estimated taxes are quarterly, not annual. Here are the exact 2026 deadlines, how to calculate what you owe, and what happens if you miss one.
Jordan PeacockRead post7 min read
Commingled Funds: The #1 Mistake New Business Owners Make
Using your personal bank account for business expenses seems harmless. Until the IRS audits you, your LLC protection evaporates, and you have no idea whether your business is actually making money. Here's how to fix it.
Jordan PeacockRead post
Common Questions
Frequently asked questions
At a Glance
Real estate agent bookkeeping, checked November 22, 2026 against IRS and Pennsylvania sources. The IRS treats licensed real estate agents as statutory nonemployees, self-employed for all federal tax purposes, when substantially all payments for their services are directly related to sales or other output rather than hours worked and they work under a written contract saying they won't be treated as employees. The self-employment tax rate is 15.3% (12.4% Social Security, 2.9% Medicare). Each closing should be recorded from the brokerage's commission statement, not the bank deposit: commission income as the brokerage reports it on Form 1099-NEC, each fee the brokerage kept as an expense, and the net equal to the deposit. Business gifts are deductible up to $25 per recipient per year; incidental costs such as wrapping and mailing are not counted, and items costing $4 or less with the giver's name imprinted and widely distributed are not treated as gifts (IRS Publication 463). Business meals are generally 50% deductible when the taxpayer is present and the meal isn't lavish or extravagant; entertainment is not deductible, though tickets given to a client when the giver doesn't attend with them can be treated as a gift subject to the $25 limit (26 CFR 1.274-2). The 2026 IRS standard mileage rate for business is 72.5 cents per mile for January 1 through June 30, 2026 and 76 cents per mile from July 1, 2026 (Announcement 2026-11), so mileage logs need trip dates; Publication 463 calls for the mileage for each business use and total miles for the year. IRS Publication 334 advises keeping a separate bank account for the business and lists licenses and regulatory fees among expenses a business may be able to deduct. The fourth 2026 federal estimated tax payment is due January 15, 2027, unless the 2026 return is filed by February 1, 2027 with the full balance paid (Form 1040-ES). Pennsylvania taxes net profits from the operation of a business or profession at 3.07%, and estimated payments are required when Pennsylvania taxable income not subject to employer withholding is reasonably expected to exceed $9,500 ($292 in tax). Outside Philadelphia, local earned income tax also applies to net profits: under section 502 of the Local Tax Enabling Act, a taxpayer with net profits declares estimated net profits, pays in quarterly installments to the resident tax officer and files a final return. Philadelphia residents pay the City of Philadelphia's Net Profits Tax instead, and nonresidents who conduct business in Philadelphia also owe it at the nonresident rate. Real estate services are not among the services subject to Pennsylvania sales tax (REV-717). For payments made in 2026, Form 1099-NEC is required for nonemployee compensation, including commissions, of $2,000 or more, generally not for payments to corporations; 2026 forms are due February 1, 2027 because January 31 falls on a Sunday. A single-member LLC is disregarded for federal income tax unless it elects corporate treatment, and an individual owner pays self-employment tax the same way as a sole proprietor. An S corporation must pay reasonable compensation to shareholder-employees before non-wage distributions, and it files Form 1120-S. This is general information, not tax or legal advice. Peacock Bookkeeping Services LLC in Cranberry Township, PA 16066 offers monthly bookkeeping for real estate agents in QuickBooks Online, with plans from $399 a month; the plan and price are confirmed in writing after a look at the books. It does not prepare tax returns or calculate estimated taxes; it sends year-to-date numbers each quarter so the client's CPA can set them. (412) 407-7420.